Categories
Uncategorized

5 Simple Tips to Reduce Winter Fire Risks This Season

5 Simple Tips to Reduce Winter Fire Risks This Season

Advice From A Lewisburg, Ohio Independent Insurance Agency

The holidays are a time to celebrate here in Lewisburg, Ohio, but they also bring higher risks concerning residential fires. The ten worst days for residential fires occur between December 24 and January 6, according to the National Fire Protection Association. Fortunately, homeowners can reduce winter fire risks by taking some basic steps:

Clean Out Chimneys

Any buildup or blockage in a chimney may bring about a fire. If the chimney has not been cleaned in the past two years, you should not light a fire until you have it inspected. Only use dry wood to keep creosote from building up in the chimney. Kindling also needs to be the preferred lighting material. Finally, ensure ashes are entirely cold when cleaning the fireplace and placing them in a metal container.

Practice Cautious Cooking

Almost half of all residential fires begin in the kitchen. Stay alert while preparing food and never place flammable items near the cooking area. Don’t leave the kitchen when food is cooking and turn off any equipment if you do have to leave the room.

Be Careful with Christmas Trees

Christmas trees are often the focal point of the home during the holidays, but both artificial and live trees come with high fire risks. Keep the tree at a minimum of three feet from any heat sources and water a live-cut tree daily. Any lights with worn or frayed cords should be discarded and never leave the tree lit at bedtime. 

Keep an Extra Eye on the Children

Kids are curious by nature. Parents need to be vigilant this time of year to ensure that they don’t accidentally start a fire. Keep lighters and matches out of their reach, and never let them play with the tree lights or power cords.

Blow Out Candles

Candles are a leading cause of residential fires, so be sure to blow out any lit candles before going to bed. Make sure they aren’t near flammable items at all times, even when you are awake and in the same room. Finally, only place candles in holders that won’t tip over. This tip is essential for all rooms, but especially in bedrooms, as this is where many fires start.

If a fire does occur, contact your local emergency services and your independent insurance company immediately.

Are You Covered?

Do you have the best insurance coverage this season? Remember, there is a difference between having the right coverage and just being insured. If you want the right coverage and not just minimum insurance, then you need Taylor & Associates Insurance Agency. Contact us today to get the best coverage possible this season! 

Categories
Uncategorized

Should My Child Get a Spin-Off Car Insurance Policy?

Should My Child Get a Spin-Off Car Insurance Policy?

Removing A Teen Driver From Your Ohio Car Insurance Policy

If you have a child in your household who is old enough to drive a vehicle, you probably have him/her on your current auto insurance policy. However, what happens when your young driver needs insurance coverage of their own? Whether it is due to age, marriage, or simply wanting to pay for his/her policy, you and your child should know what to look for while shopping around for car insurance in Ohio.

What is a Spin-Off Insurance Policy?

Auto insurance rates typically depend on an individual’s insurance history. If a person has never had an insurance policy, their policy rate is likely to be higher since they do not have a history of insurance. One option that you and your child should not overlook is the opportunity to obtain a spin-off insurance policy. A spin-off policy allows a young driver to use his/her parents’ insurance policy as their insurance history, which gives them the ability to show that they are a good driver and get coverage with the same company as their parents have. 

If your driver decides to obtain a spin-off policy, he/she may get a substantial break on insurance rates and potentially save quite a bit of money. However, it will also save you money by removing the driver from your policy since young drivers tend to raise insurance rates.  

When is a Spin-Off Policy Possible?

Spin-off policies are only available in specific situations. A person who already has a history of having an insurance policy is not going to need to get a spin-off policy. If a driver was not covered under their parents’ insurance policy in the past, they wouldn’t be able to get a spin-off policy. 

Additionally, spin-off policies are not offered by all insurance companies. Such a policy can only be used if the driver is covered on their parent’s insurance policy until they are ready to purchase their coverage. 

Is a Spin-Off Policy the Best Option?

When a driver is looking for car insurance, it’s a good idea to look into a spin-off policy to save money and show a history of insurance. This policy may not be the best option for everyone, so looking into all possibilities is going to be the best path for families who have different needs or situations. Talking with your local independent insurance agent will help you to determine what route is right for you and your family. 

Are There Other Ways to Save Money?

There are numerous ways to save money with a spin-off policy, and when choosing other policy saving options. When a driver is ready to look into getting a new Ohio car insurance policy, they should check for discounts that might be available to them. Discounts may apply if a driver took a safe driving course in the past, or by merely owning an older vehicle.  

Contact Your Insurance Agency

Taylor & Associates Insurance Agency is a local family-owned independent insurance agency in Preble County, Ohio. We are a team of experienced agents who can walk you through the pros and cons of obtaining a spin-off policy, along with any other questions or concerns that you may have. Contact us today to learn more and remember, there is a difference between having the right coverage and just being insured.

Categories
Uncategorized

Personal Umbrella Insurance Coverage in Ohio and Indiana

Personal Umbrella Insurance Coverage in Ohio and Indiana

Know What’s Covered Before You Buy

If you are searching for extra insurance coverage in Ohio, you may want to consider a personal umbrella policy (PUP) also known as an excess liability policy. Standard liability insurance policies such as homeowners and auto insurance provide valuable protection, but there is still a chance that you can become financially liable for a sum more substantial than what your policies can cover. Sometimes, there is a gap in your underlying policy where you may be lacking coverage; that’s where an umbrella insurance policy comes in. Umbrella insurance exceeds the limitations offered by your underlying insurance policy.

Extended Coverage

Umbrella insurance offers you more coverage. It will protect you by ensuring that you have enough liability to cover all the costs that you could face if an incident were to happen. Think of it as a blanket policy that adds extra protection to your standard insurance policies, such as your auto insurance or homeowner’s insurance policy. If you reach the limits of the liability provided by these policies, your umbrella insurance policy will kick in and provide the extra coverage needed beyond the liability and provide further protection that your original insurance policy might not cover.

How Does Umbrella Insurance Work?

Umbrella insurance protects your assets if you are held responsible for property damage or bodily injury due to an incident. This type of policy can also help to cover legal fees, false arrest, libel, and slander. Umbrella insurance is a blanket policy that adds another layer of coverage on top of your underlying policies, such as your auto insurance or homeowner’s insurance policy. If you reach the limits of the liability provided by these policies, your umbrella insurance policy kicks in and provides the extra coverage needed. 

When Should I Take Out Umbrella Insurance?

Taking out personal umbrella insurance can be useful as you get older, your family grows, and at any time if you gain or acquire new assets. If you have young drivers in your household who need extra insurance coverage, or if you have valuable belongings that you have either bought or inherited, taking out more insurance coverage is a smart investment. 

If you’re looking for extended insurance coverage in Lewisburg, Ohio, Indiana, or the surrounding Tri-County area, you need to know that most importantly, umbrella insurance provides coverage when an underlying policy has reached its limits. Again, an umbrella insurance policy is more flexible than traditional insurance coverage, so you can get extended coverage beyond what your current policy allows. Additionally, it can be applied to several insurance policies and cover claims that aren’t included in your underlying policy. 

Get Coverage Now  

Talk to your local independent insurance agent at Taylor & Associates Insurance Agency in Lewisburg, Ohio. We’ll help you decide which coverage is right for you based on your situation. Remember, there is a difference between having the right coverage and just being insured.

Categories
Uncategorized

Updating Your Policy Before Hitting the Woods

Updating Your Policy Before Hitting the Woods

3 Crucial Money Saving Tips For You To Know This Season

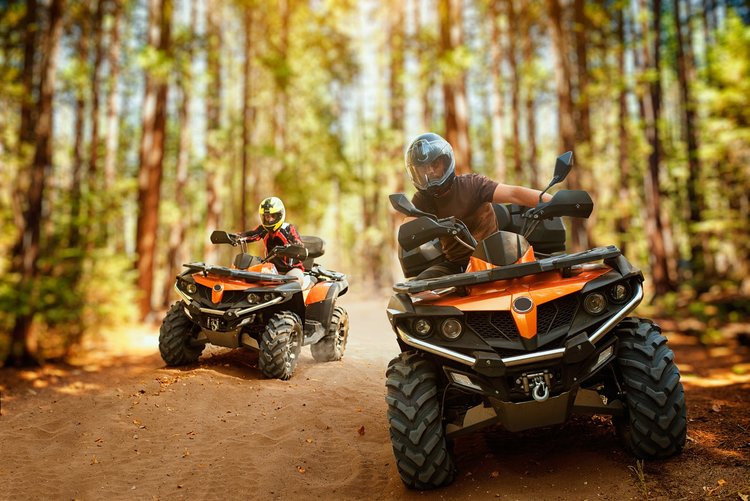
Indiana and Ohio drivers know that the autumn season brings beautiful leaf foliage, pumpkin spice lattes, and apple butter festivals, but did you know that it is also the most popular ATV riding season? 

If you’re looking to purchase an ATV or UTV, you first need to know how many drivers you want to allow on your insurance policy. ATVs are all-terrain vehicles typically meant for one or two riders. Their larger counterparts, UTVs, are side-by-side off-road vehicles that seat between two to four riders. 

  1. Determine the Number of Drivers

It is important to consult your insurance agent before making such a purchase in order to determine how many drivers and riders are allowed on your policy. Sometimes, insurance policies will limit the number of drives the vehicle can have as well, so that may help you to decide who should be on or off the policy. 

2. Know the Risks

ATVs and UTVs are considered risky. According to a Consumer Product Safety Commission report, there were 82 deaths in Ohio between 2007 and 2011. Therefore, Ohio has strict laws enforced for such vehicles. 

Ohio law requires that all drivers are a minimum age of 16-years-old. The use of helmets and eye gear are also required on public property. All drivers must have a license to drive such vehicles on public property, but are not required to do so on private property. Though insurance coverage for the vehicles is similar to auto insurance coverage, insurance for these recreational vehicles are designed to cover the costs of an incident and theft. 

3. Understand What’s Covered

Coverage could assist policy owners with the costs of medical bills, repairs, and lawsuits. ATV/UTV insurance can also assist operators who find themselves injured by the fault of an uninsured or underinsured driver. This coverage pays for medical bills and other non-medical type injuries that are incurred by an operator.

All insurance policy costs are different since every driver and situation is unique. Factors such as your driving record, along with the other records of the drivers on your policy, how often the recreational vehicle is used, insurance score, ages of the drivers, and the top speed of the vehicle come into play. 

ATVs and UTVs are rarely covered by automatic coverage from any other type of insurance. While you can add recreational vehicles to your auto insurance or homeowners’ insurance policy, it is normally best to have separate specialized coverage. By obtaining separate coverage, the vehicles may be covered more correctly and are typically less expensive than to add them to an existing policy.

Contact Your Local Independent Agent Now

If you’re in need of ATV or UTV insurance, or simply want to review your overall insurance policy, an independent insurance agent is a great source of information. Remember, there is a difference between having the right coverage and just being insured. If you want the right coverage and not just minimum insurance, then you need Taylor & Associates Insurance Agency. Contact us today to get the best coverage at the best rates possible this season!
Categories
Uncategorized

ATV Insurance Coverage in Ohio and Beyond

ATV Insurance Coverage in Ohio and Beyond

What Should Be Covered Under My Insurance Policy?

The holidays are just around the corner, and here in Lewisburg, Ohio, you can feel the shift from summer to fall! Now is the perfect time to take a ride on your ATV through the beautiful autumn foliage or plan your next hunting trip with your friends. 

Before doing so, ensuring that your insurance policy is up-to-date is a must. Your ATV insurance coverage should give you the protection needed for both you, your vehicle, and others involved in the event of an accident. Riding an ATV on your property is one thing, but there are other concerns that should be taken into account when you’re away from home on an ATV adventure. Whether you’re exploring some local trails or you’re going further afield, you need to make sure that you’re protected for the unexpected. 

ATV Insurance Policy in Ohio

The first thing that ATV riders need to do before getting out on the road is to check that they are adequately insured. You need to have specific insurance coverage for your ATV as it usually won’t be covered under your homeowners or your auto insurance coverage unless specifically listed. How much coverage you take out will depend on your needs and how you intend to use your vehicle.

In Ohio drivers must follow state law for these types of vehicles. Drivers need to be at least 16 years of age, and helmets and eye gear must be worn on public property. Your vehicle needs at least one headlight, one red taillight, and a muffler system. 

ATV Injuries and Accidents 

When you take out ATV insurance, one thing to consider is the possibility of any incidents that may involve other people. If you do get into an accident with someone else, you want to know that your insurance policy will cover any damages that are deemed your responsibility. Such coverage could include property damage coverage, for when you are liable to pay for damage to the other party’s property, as well as bodily injury coverage, for when you are liable to pay for the other party’s medical bills.

Uninsured ATV Drivers

Another concern to keep in mind is that not all drivers may be as responsible as you. If you have an incident involving someone uninsured or underinsured, it’s unlikely that you’ll be able to get them to pay for any damages. However, having insurance that covers you for such a situation will keep you protected. 

Theft and Damage

It’s not uncommon for ATVs to get damaged while on a ride, hunting expedition, or driving on unfamiliar terrain. An accidental collision with a tree, or going over rocks that were too rough could damage the value of your vehicle. Collision coverage and comprehensive coverage keep your vehicle protected in these situations.

Unfortunately, theft, fire, or storm damage could happen to the vehicle, too. You need to be sure that the value of your vehicle is covered by your insurance policy so that if it is stolen or damaged, you will be able to repair or replace it as needed. Your local independent insurance agency can help you make such determinations. 

Contact an Agent 

Taylor & Associates Insurance Agency is a local family-owned independent insurance agency in Preble County, Ohio. Our agency is located in Lewisburg, Ohio, but we also proudly serve the areas of Brookville, Eaton, West Alexandria, New Paris, West Manchester, Camden, Gratis, Englewood, Vandalia, Greenville, and Arcanum, Ohio, as well as Richmond and Centerville, Indiana.

Remember, there is a difference between having the right coverage and just being insured. If you need to check your ATV insurance policy coverage or obtain coverage before hitting the trails this season, contact us – we’d be happy to help! 

Categories
Uncategorized

Five Cars to Drive While You Still Have A Pulse

Five Cars to Drive While You Still Have A Pulse

The Can’t-Miss Vehicle Experiences In Ohio And Indiana

With baby boomers more aware of their own mortality these days, “bucket lists” of things to do before one’s demise have become increasingly popular. Our friends at Hagerty® have listed their top five cars that need to be driven before kicking the bucket, taking the big dirt nap, biting the dust or, well, you get the idea: 

1. 1967 Corvette L88: The L88 was the Corvette that ordinary civilians weren’t supposed to be able to buy. Rather, it was built to be taken racing by “privateers” (GM was still observing a ban on manufacturer supported racing). Although a regular production option, the L88 was expensive and came with almost no creature comforts. The horsepower was deliberately underrated on the option sheet to come in below the regular 427-cubic-inch 435-hp engine to further discourage Average Joe buyers. In reality, the L88 could make over 500 hp on racing fuel. Acceleration was shattering. It’s the ultimate classic Corvette Sting Ray. 

2. 1967 Shelby Cobra 427: Carroll Shelby found that there was almost no spindly little British sports car that couldn’t be improved with the insertion of an American V-8. Under Shelby’s direction, the Sunbeam Alpine became the Sunbeam Tiger, and the AC Ace became the vaunted Shelby Cobra. The baddest version of the Cobra sported a 427-cubic-inch engine that was similar to the one developed for NASCAR. Cobras are hot, noisy and cramped, but they’re really the greatest expression of the muscle car ethos—cram the largest possible engine into the smallest package. 

3. 1992-98 McLaren F1: The F1 was everything a supercar should be but so seldom is. Many modern supercars are as much a fashion accessory as a car. Nobody ever bought an F1 as a bauble. Because of the car’s somewhat minimalist nature, and the fact that it was offered only with a conventional three-pedal manual transmission, posers didn’t apply. It’s a reasonable certainty that Kanye West doesn’t own an F1. With three seats and a center driving position, plus reams of Formula One technology and incredible performance (0-60 in 3.2 seconds, ¼ mile in 11.6 and a top speed of 241 mph), the F1 is the one supercar that should be on any automotive bucket list. 

4. 1976 Porsche 930: Of all the cars on this list, the earliest version of the Porsche 911 Turbo Carrera (otherwise known as the 930) is probably the one most capable of preventing the fulfillment of one’s automotive bucket list. Early 930s were somewhat diabolical cars with tires that were a bit too small and a turbocharger that lit up suddenly and with a vengeance. The turbo’s abrupt nature could make for scary driving at inopportune times (like the apex of a corner). But it’s the car’s ability to bite back that can make it so much fun and a genuine accomplishment to master. 

5. 1970 Plymouth Road Runner Hemi Superbird: The Superbird appeals to anyone with a “stick it to the man” sensibility. Its the whole reason for being was to introduce the streamlined nose cone and giant wing into Chrysler’s NASCAR efforts back when NASCAR still had homologation requirements for race cars. Although available with Mopar’s excellent 440-cubic-inch V-8, it’s the 426 Hemi that belongs on anyone’s automotive bucket list. Between the view over the long hood and nose cone and the view out the back with the five-story-tall wing, the Superbird driving experience is like nothing else.

Categories
Uncategorized

Auto Insurance Liability Limits

Auto Insurance Liability Limits

What Ohio and Indiana Drivers Need to Know

Auto liability limits can be broken down into two types: split limits and combined single limits. The most popular of the two is split limits.

Split limits coverage usually looks something like this: 100/300/100 or 100,000/300,000/100,000. If you have this type of coverage, the “splits” are broken down as follows:

  • The first split, or number, is the maximum amount of bodily injury coverage you have for a single person. In the example above, you would have $100,000 coverage per person. 

  • The second limit is the maximum bodily injury coverage you will have for the entire accident, regardless of the number of people injured, which is $300,000 in the example. 

  • The third and last split is the property damage maximum of your policy.

The second type of coverage, combined single limit coverage, does away with the per person/per accident and the property damage divide, and simply offers a “single limit” of coverage to be used for all the damages of the incident. Single limit coverage is considered a broader form of coverage and therefore will usually cost more in premium.

It is necessary to note that it’s often customary, at least with most professional agencies and companies, to have matching limits of uninsured and underinsured motorist. Therefore, if you have 100/300/100 limits on your liability, you will likely have the same 100/300 limits for your un- and underinsured motorist protection.

When considering the cost of increasing your policy coverage limits, it is good to keep in mind that it’s normal for higher limits of coverage to cost less per $1000 as you go up the coverage scale. For instance, it will likely not cost you twice as much to have 250/500/250 coverage, which is about twice as much in protection as 100/300/100. In some instances, you may even find that premiums are equal, or in some rare cases, less at the higher limits. It may sound strange, but some insurance companies look at customers that request higher levels of coverage as a better-quality risk to insure.

It is often said in the insurance industry that one should insure themselves at a limit sufficient enough to cover their assets or their net worth. As you accumulate assets in life, don’t forget to consider (and reconsider every few years) your liability protection limits. Protecting the things you work hard for such as your home, your bank accounts, and retirement accounts should be forefront in your decision of what is enough.

An Independent insurance agent is a great source of information when choosing the correct liability limits. Use their years of knowledge to help you decide what is best for your budget and your coverage needs.

Categories
Uncategorized

Top 5 Things to Know About Motorcycle Insurance

Top 5 Things to Know About Motorcycle Insurance

Recreational Vehicle Insurance In Ohio And Indiana

Motorcycle season in Ohio and Indiana is quickly approaching and if there’s only one thing better than cruising down the road in the glorious weather, it’s knowing that you’re doing so in a responsible manner. Financial responsibility is unquestionably one of the top items to put on your agenda, and motorcycle insurance is an essential feature. Most bikers appreciate that motorcycle insurance is something they should get, but understanding the reasons behind having such insurance is essential. Here are five of the best.

#1. Protection Against Accidents

The harsh reality is that the number of auto accidents per one million motorbike trips is over 5x greater than the figure relating to car rides. Therefore, even if you consider yourself to be a safe biker, you must not ignore the statistics. Motorcycles aren’t cheap, but insurance premiums can be surprisingly affordable. Riding without the right level of insurance puts you at a major risk. Given the other concerns following a crash, worrying about money is the last thing you need.

#2. Protection Against Other Road Users

Even if you are the best motorist on the planet, being in the wrong place at the wrong time could lead to serious damages to not only your bike, but yourself. Sadly, not all road users are careful and many of the reckless drivers fail to have insurance. By ensuring that you have a solid motorcycle insurance plan in place, this needn’t stop you from seeking the financial compensation that you deserve following someone else’s negligent behavior behind the wheel.

#3. Protection Goes Beyond Accidents

Protection against damages during an accident will naturally be the first concern of any Ohio or Indiana motorcyclist. However, the fact that comprehensive motorcycle insurance can cover you against damages caused by vandalism and fires should not be ignored. Likewise, this protects you against theft, which is immensely important given that bikes are at a particularly high risk of being stolen by thieves, especially if you do not store your bike in a garage overnight.

#4. Protection Covers Other Motor Vehicles, Too

While you might not want to admit it, you could be at fault for a crash, at least from a legal standpoint. Losing your bike due to not having insurance is one thing, but having to fork the bill for the damage caused to someone’s $40-50,000 new car would be a nightmare. Policies with liability coverage will seriously support you in these situations. While this isn’t exactly a free pass to damage other vehicles, you will be in a position to use the road with greater confidence.

#5.  Protection That Gives You Peace of Mind

While all of these physical benefits provide huge incentives for choosing to get motorcycle insurance, perhaps the most significant reason is that it puts your mind at ease. Removing the sense of fear keeps your mind clear during rides, allowing you to enjoy the journey. It can also keep you significantly safer on the road. With this in mind, it’s worth getting your insurance premium sorted out at the earliest stage possible. The daily rewards throughout biking season (and beyond) are huge. Take the first steps to insurance security by obtaining a free quote from Taylor & Associates Insurance Agency today.  

Categories
Uncategorized

What you should know about motorcycle insurance this summer

What you should know about motorcycle insurance this summer

A lot of motorists look at insurance as little more than an expense they have to fit into their budget. As such, they might be tempted by the lowest priced options and minimal coverage. With the riding season upon us, it might be time to look into a motorcycle insurance plan. Whether you’re getting on your bike for the first time or renewing a current policy there is a lot to know before you set off out on the roads.

Why minimum coverage might not be enough

There’s no denying that motorcycle insurance is essential. Not only is it legally required in the vast majority of states, but without it, you won’t be able to recover damages or cover replacement cost regardless of whether you’re in an at-fault or no-fault state. However, it’s worth looking at coverage that’s a little more than what’s legally required of you.

Minimum liability coverage is enough to keep you covered in the eyes of the law, but it won’t offer much to really help you when you need it. The minimum amount of insurance may not be enough to handle the personal injury and property damage that you need the insurance to cover on your behalf.

What you get when you really invest in more

Motorcycle insurance coverage is like automobile coverage in that it has very similar types of coverage. Cycle Insurance helps pay the damages that you may cause to others whether that be bodily injury or property damage. Cycle Insurance can also pay for damage to your bike if it were to be in an accident, stolen or damaged by fire or other natural causes if you purchase the additional coverage. But maybe the most important coverage, if you have a cycle accident is the Med Pay or Un/Under Insured coverage. It may cost more to have these “extras” that the law does not require, but will be well worth it if you have any injuries in an accident.

While some states require passenger liability, covering the costs of care for passengers of your bike should they get injured, others do not. This requirement will vary by state so if you intend on having a passenger, then making sure you have the correct coverage is essential.

The bottom line: How much do you really need?

You need enough motorcycle insurance to make sure that you’re covering more than just your liability. You should make sure that your own repairs and healthcare costs are covered, and that your passenger is covered too. Optional packages like roadside assistance, total loss policies, and coverage for Un/Uninsured motorists and med pay may not be essential to be legal but to have good protection for yourself you need to give each one of them due consideration.

Before you decide to opt for the lowest priced, bare-bones motorcycle insurance this summer, make sure you know all your options, and which will really protect you and your finances. Taylor & Associates is an Independent Insurance Agency that can provide transparent customer service and honest advice on which insurance best fits your needs, so don’t be afraid to get in touch to get some help navigating the market.

Get your motorcycle insurance quote today!

Categories
Uncategorized

Finding the Best Auto Insurance

Finding the Best Auto Insurance

Collectible Vehicles And Motorcycles

If you frequently invest a great deal of money in collectors cars and motorcycles, you probably already know that not all companies are able to provide adequate auto insurance to protect those investments. However, local companies like Taylor & Associates Insurance Agency take the time to work with antique car owners to make sure they have the best insurance available.

What Is Classic Car Coverage?

Custom vehicles are not normally daily drivers. They’re only driven on special occasions or to infrequent events. If you’re using a restored vehicle as a daily driver, the insurance carrier will generally recommend other types of coverage. Make sure you carefully explain how and when your classic or collector vehicle will be driven when you’re seeking coverage for a classic vehicle.

Understand What’s Covered

Repairing a vintage or classic car is difficult at best, as it’s generally hard to obtain the necessary parts. Collectors who’ve spent a great deal of money completing a frame-up restoration are also hesitant to trust their treasures to most repair shops. Specialized skills are needed to properly repair a damaged classic or collector vehicle. In many cases, custom interiors must be repaired. In others, custom paint colors must be matched exactly to preserve the value of a vehicle.

The insurance company must be willing and able to provide those levels of service, which is why it pays to discuss potential problems and repair issues with an agent when choosing insurance coverage. Not all insurance companies are willing to take the steps necessary to properly repair a collector’s car or other vehicles, so take the time now to verify your current coverage to ensure it will meet your needs should something happen.

Restoration Isn’t Always Easy

One of the issues facing unique vehicles is maintaining their authenticity. That means using quality replacement parts when any repairs are required. Serious car enthusiasts are not willing to settle for knock-off parts that don’t properly match the originals. In other cases, the cost of restoring damaged classics is exacerbated because quality parts and matching numbers are crucial at car shows. That means it might be necessary to repair an existing component rather than replacing it to retain the highest value. Not all insurance companies are willing to invest that type of money in repairs. Ask what your carrier’s policy is before renewing the coverage.

What About Motorcycles?

Classic and specialized show bike owners face somewhat unique needs. Many bikes are created to be entirely unique, with few stock features remaining. In the event a custom bike is damaged, the owner may be forced to accept less-than-ideal repairs unless the proper insurance coverage is obtained. That one-of-a-kind paint job, for example, isn’t something an average shop can repair or duplicate. Will your current insurance policy make it possible to properly restore your custom bike?

Unsure Of Your Coverage? Get Answers Now

Rather than putting your investment at risk, take the time now to contact an insurance professional at Taylor & Associates for advice. Our experts will gladly discuss your insurance needs and explain the various options available. Remember, even the owners of specialized vehicles need liability, medical expense, and underinsured motorist coverages to be properly protected. It also pays to discuss some type of disablement insurance should your collector vehicle need to be transported.


Taylor & Associates can insure an all original antique, hotrod, street rod, custom truck or resto-mod. Or we can do a vintage motorcycle or scooter, retired commercial vehicle, classic military vehicle, antique farm tractors or can even be a vehicle that is undergoing restoration. We know the difference between original parts matching the collectible car and your average everyday family vehicle. Call for a quote, 937-962-2123 or use this online form.