Categories
Uncategorized

Is It Comprehensive Or Is It Collision?

Is It Comprehensive Or Is It Collision?

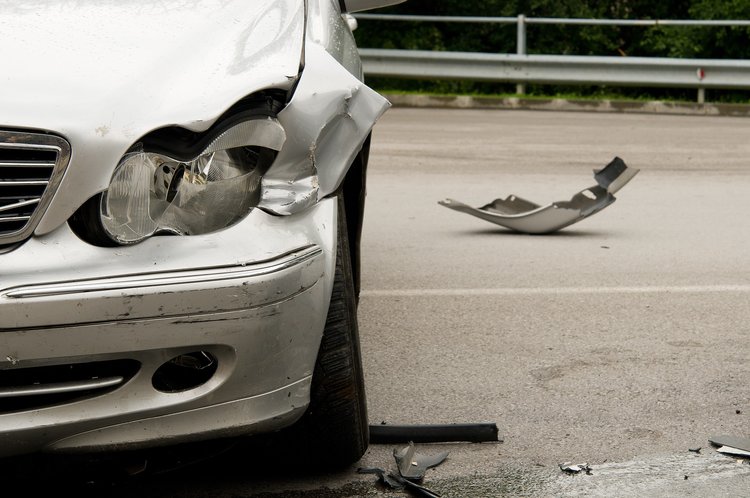
Your driving down the interstate and suddenly there is a huge hunk of something metal in your lane. You only have a split second to react, it is either hit that muffler that has fallen from another vehicle or swerve into the next lane and hit the semi truck next to you. You have no choice, you try your best to straddle it but it is just to large… CRUNCH!
Damage to your car is pretty extensive. Your bumper is trashed, your lower grill is broken and fluid is leaking on to the road. Needless to say the vehicle is disabled and will need to be towed.

So you call your insurance agent and he starts asking you several questions. What does it matter you ask? Plenty! The answer to your agent’s questions will determine what type of loss this is, comprehensive or collision, and that will determine what your deductible is in the best case and if you have coverage or not in the worst case.

Here is the bottom line. If the object was moving, “a projectile” then it will most likely be considered a comprehensive claim. Most of the time this is a lower out of pocket expense to you due to a lower deductible. In some cases it may mean the difference of having coverage or not as some of us have chosen to forgo the more costly premium associated with Collision coverage.

The difference between Comprehensive and Collision is very extensive. For more information on coverage questions, contact us by email or call us at 937-962-2123.

Taylor & Associates Insurance Agency is proud to support our local community with quality insurance coverage from reputable insurance companies like ALFA Insurance, Allstate Insurance, Celina Insurance Group, Dairyland Insurance, Progressive Insurance, The Hartford Insurance and Western Reserve Group. We provide car insurance for the Tri-County area including Lewisburg, Brookville, West Alexandria, Eaton, Eldorado, New Paris, West Manchester, Arcanum, Greenville, Richmond, Preble County, Montgomery County, Darke County, Wayne County IN.
Categories
Uncategorized

4 Secrets To Discourage Car Theft

4 Secrets To Discourage Car Theft

How to Outsmart Car Thieves

Did you know that according to the NHTSA, a car is stolen every 45 seconds in the U.S. for a total value of $4.1 billion? Nearly half of those affected are due to driver error — common sense mistakes that give thieves an easy target.

But even common sense won’t necessarily prevent car theft. Smart moves like parking in well-lit areas, locking car doors and windows, and never leaving the keys in the ignition may not be enough to deter professional thieves. How can you prevent your car from becoming a statistic? Follow these proven precautions:

Become an Etch Artist —Have your vehicle identification number (VIN) etched into your windshield, windows and parts. This helps discourage thieves interested in your car for the stolen parts market.

Create an Obstacle —Make your car not worth the hassle by installing a physical deterrent. Locks available for the steering wheel, gearshift, hood and tires prevent access or movement, while a steering column lock prevents hot-wiring.

Shut Thieves Down —If your car didn’t come with a smart key or wireless ignition authentication system, prevent an easy getaway by installing an ignition kill switch, fuel disabler or tire deflator.

Install a GPS Tracker —Make it easier to recover your vehicle if it is stolen by installing a GPS tracking device. Some models even allow you to shut off the engine remotely using a smartphone app.

Categories
Uncategorized

Replacement Cost Homeowners Insurance

Replacement Cost Homeowners Insurance

The term replacement cost comes in to play mostly in two parts of homeowners insurance.

1. Structure – Usually the replacement cost on a structure refers to the dwelling but could possibly be about other structures as well. When considering what amount of coverage you will need on your house, a good agent must take into consideration what it would cost to rebuild your house. This is the amount that is needed to completely rebuild from the ground up after a total loss such as fire or tornado. It includes removing what is left of the old structure, preparing the sight and then rebuilding the entire structure. If a mistake has been made or you choose not to have the house insured to replacement value, you may suffer great financial setback when a loss occurs that results in a reduction of your loss settlement due to the penalty applied in this type of situation (Coinsurance Penalty.)

2. Contents – From furniture to appliances to socks and shoes, when you think about all the things your house contains and how much it would cost to replace each item new at the store, you will start to understand the importance of replacement cost. Most people never consider how much stuff they have in their homes but if you ask someone who has had a house fire, they can tell you it is a lot and that you want to make sure that you are property insured. It is never a convenient time to have an insurance claim. More than that, no matter how good of a bargain shopper you are, not all your contents will be on sale at the exact same time when you need to replace them all due to a claim.  If you don’t have replacement cost for contents coverage on your homeowners insurance policy you will be forced to depreciate (reduce) the cost of each content item by an amount relative to its age. Imagine this reduction on every item in your house all at once. This is why replacement cost on contents is essential in our opinion.

Your home is most likely your biggest asset, protect it correctly. Make sure you see a professional independent insurance agent to help you get the correct coverage for you and your family.

Even if we are not your agent you can contact us by email or at 937-962-2123 to set up a free consultation about your homeowners insurance.

Celina Insurance Inventory Brochure

Categories
Uncategorized

What Is Identity Fraud Restoration Coverage?

What Is Identity Fraud Restoration Coverage?

Identity Theft is running rampant. Cyber related crimes including Identity Theft are increasing 10 fold in the last few years alone and are projected to become even worse. It is important that you consider protecting yourself.

You can protect yourself from Identity Theft in several ways:

1. Being proactive and smart when in the market place whether online or out shopping in a traditional brick and mortar store.
2. Subscribing to a service that will monitor you credit.
3. Freeze your credit with the credit bureau.

No matter what level of protection you choose, I would ask that you consider one more item that may benefit you. Identity Theft Restoration Service as an optional coverage on your Homeowners Insurance policy.

Even when you have done your best to protect yourself you may still find yourself a victim of Identity Theft. If you do become a victim you will be extremely happy to have chosen the optional coverage of Identity Restoration on your homeowners insurance policy.

What does ID Restoration do for me you ask. Well for one it will help you make contact with all the credit agencies and put them on notice that you have been victimized.

Second, it will help you file claims with the local, state or federal agencies as appropriate. Knowing who to contact and having help doing so will likely be a great relief to you if you suddenly find yourself a victim of ID Theft.

Victims of ID theft have said that getting your financial life back is like having to take on a new part time job. All the while you find yourself unable to function financially as you have become accustomed as your accounts may be in a state of turmoil at the bank and/or other financial institutions. All you want at this point is to have everything returned to normal as soon as possible.

Identity Fraud Coverage is usually a very affordable optional coverage on your homeowners policy. It is normally offered with a predetermined limit or choice of limits that act as a cap to what benefit your policy will provide. Most coverage will be $5000 or more of benefit and will cost in the neighborhood of $10-25 per year. Be sure you ask what the limit is when you add this coverage to your policy.

Not all insurance companies offer the same combination of coverage on their Identity Theft Protection and some companies don’t offer the coverage at all.

Want to know if you have coverage on your current policy? For more information about ID Coverage and your homeowners insurance policy, contact us by email or phone at 937-962-2123.

Categories
Uncategorized

Clarifying Auto Insurance Coverage

Clarifying Auto Insurance Coverage

So you lend your car to a friend, and he gets into an accident. Who’s financially responsible — you or the friend? What about a situation when you need to rent a car? Should you opt for the rental car insurance or will your existing insurance cover you in the event of an accident? Put another way, is your car insurance tied to you or your car? The answer: It depends.

Who’s responsible if your friend crashes your car?
Let’s tackle the first scenario when your friend crashes your car. Personal auto insurance is attached to the vehicle in this case. If your friend is found liable, you would likely be responsible and your car insurance would then apply.

Your friend’s insurance would be secondary, and his provider would only step in if the damage exceeds your insurance limits. If your friend is uninsured, however, and the damage is extensive and involves other vehicles, the affected parties could look to you for property damage reimbursement and medical expenses. And note that even if your friend didn’t have permission to use your car, this can be difficult to prove.

Do you need rental car insurance?
Now let’s talk about the second scenario: renting a car. In this case, most personal auto insurance policies go with the driver. If you have comprehensive and collision coverage in addition to liability coverage, you may not need rental car insurance.

If you damage a rental car, the rental car company could charge you for loss of use since a vehicle in repair isn’t rentable. This may not be covered by your insurance policy. And if you need to rent a car while traveling for work, be sure to check your coverage with your employer.

Understanding the scope of your current coverage is key before lending out your car or booking a rental. Make sure you’re familiar with your policy and coverage and get in touch if you have any questions.

Categories
Uncategorized

Home Warranty Vs Home Insurance

Home Warranty Vs Home Insurance

Did you know that home warranties aren’t just for new residences? Homeowners can buy a warranty for their existing home and have this extra protection along with their insurance. Find out how the two types of coverage differ, and see if buying a home warranty makes sense for you.

Coverage — Home insurance, which is usually required by mortgage lenders, typically covers your house against fire, windstorms, hail, lightning and theft. A home warranty, on the other hand, is optional and typically covers the costs for repair or replacement of the electrical, plumbing and HVAC systems as well as major appliances like the refrigerator or oven. Homeowners may opt to buy a home warranty to avoid unexpected expenses when appliances break down.

Liability — If someone visiting your home slips and falls and you’re found legally responsible for the injury, your insurance policy may provide financial assistance. Warranties, however, provide no bodily injury liability coverage.

Limitations — Insurance policies limit claims based on a dollar amount. Warranties, on the other hand, limit coverage to a specified period of time. A home warranty is essentially a service contract.

It’s important to note that a home warranty may cover the cost to fix a broken refrigerator, but you’ll likely have to use a particular service company and will still be charged a service fee. And while your refrigerator may be covered, your ice maker might not be.

Also keep in mind that some home warranties may not cover appliances that have broken due to neglected or improper maintenance.

Buying a home warranty could give you peace of mind. Just be sure to get t

Categories
Uncategorized

Vacancy And Your Insurance Policy

Vacancy And Your Insurance Policy

The insurance industry, at the company level, has been cracking down on vacancy claims, not paying claims for vacant property or reducing the coverage available for the claim. What constitutes a Vacancy a) a rental that is between tenants b) a home that you just purchased that is not yet occupied c) a home that becomes unoccupied for whatever reason. How can you protect yourself? a) know what your insurance contract defines as a vacant b) call your agent if you have any questions c) inform your agent in advance or as soon as possible if your property will be unoccupied. d) take steps to maintain occupancy of the property at a level that satisfies the contract of the company.

Click for more info

As a rule of thumb, the Vacancy Clause of a property insurance policy will activate somewhere between the 30th and the 60th day. Please know what your policy states. If the vacancy cause is activated due to being vacant for too long, the insurance provided by your carrier may be limited or cease to exist at all. Again, please know what your policy will do. If you find yourself in a situation where your property will be vacant for longer than your policy allows, it is a good idea to consider changing insurance coverage and going with a “Vacant” policy.

A Vacant policy is likely not as comprehensive as other types of policies you would have but it is designed to cover a vacant property and therefore is more likely to pay as expected on a loss. However, a vacancy policy may not cover as many types of losses as a standard Dwelling Fire or a Homeowners type policy will. One such coverage is Vandalism and Malicious Mischief. In order to have these coverages on a Vacant policy it is normally necessary that you add it on by endorsement. That means that you will be paying more premium than the standard policy. Note: some vacant policies will not offer Vandalism and Malicious Mischief coverage. Please be aware of this and know what you are missing.

Some homes are not suitable to all types of vacancy policies. There is underwriting rules and acceptability to the carrier that needs to be considered in all cases. If the home has been vacant for too long or has gone without insurance for too long, then you will likely have to search harder for a company that will accept this type of risk and you may pay somewhat more premium for the risk. If the property has been condemned or is very poor condition or has had too many losses, then you may not find coverage available at any price.

As with all things insurance. Check with your agent about your policy and particular circumstance. Don’t have an agent? Call us, we would love to help you out. Taylor & Associates has multiple vacant property carriers and can insure most vacant properties. 937-962-2123. Need a vacant dwelling quote? CLICK HERE Taylor & Associates Insurance Agency is proud to support our local community and the state of Ohio & Indiana with quality insurance coverage from reputable insurance companies like ALFA Insurance, Allstate Insurance, Celina Insurance Group, Dairyland Insurance, Progressive Insurance, The Hartford Insurance and Western Reserve Group, Safeco and State Auto. We provide car insurance for the Tri-County area including Lewisburg, Brookville, West Alexandria, Eaton, Eldorado, New Paris, West Manchester, Arcanum, Greenville, Richmond, Preble County, Montgomery County, Darke County, Wayne County IN.
Categories
Uncategorized

Policy Adjustments And Life Events

Policy Adjustments And Life Events

Everyone knows you need to update your home insurance policy when you move into a new home, but you may be surprised to learn that smaller decisions, like putting a trampoline in your backyard, could also necessitate a policy adjustment. Here are some life events that may require an adjustment to your coverage.

Moving — Anytime you move, you’ll need to amend your property and auto insurance policies to reflect your new address. If your home will be vacant or you’ll be in between houses for an extended period of time, be sure to find out what that means for your coverage so there are no surprises.

Adding a New Driver — Households with teenagers will need a policy adjustment once the teens get their licenses and start driving. There may be ways to help lessen the impact, so be sure to ask about any potential discounts, and update your information whenever your teen has a birthday.

Installing a Backyard Risk — Always let your insurance agent know if you install a pool or trampoline. Both are considered liabilities from an insurance perspective, so you may need to adjust your policy and adhere to certain safety guidelines.

Renovating or Remodeling — Many policies include a clause that voids insurance during a renovation or remodel. Be sure to notify your agent before doing any home upgrades, however minor they may be. It’s better to make sure you’re covered than to have to deal with a construction mishap when it’s too late. It’s also a good idea to have your coverage reassessed after the work is complete to ensure it’s still adequate.

Categories
Uncategorized

6 Things To Do After An Accident6 Things To Do After An Accident

6 Things To Do After An Accident6 Things To Do After An Accident

Knowing what to do after an accident is easier said than done, especially when you’re standing on the side of the road in bad weather with injured passengers and an angry driver pointing the finger at you. Here’s an accident checklist for you to follow, especially when a stressful situation makes it difficult to think clearly:

Start With Safety— Get to a safe location and switch on your hazard lights before doing anything else. If you have a roadside safety kit, set up warning triangles, light sticks or emergency cones to direct other drivers around the accident scene.

Assess Injuries— Determine if anyone has sustained any injuries so you can make an accurate report to the police and, if necessary, call for medical help as soon as possible. If you have a first aid kit, do what you can to tend to injuries while you wait for help.

Contact the Police— If there’s a dispute or the other party isn’t cooperating, contact the police. Even for minor accidents, many states require that you call the police if there are any injuries or if the damage exceeds a certain amount. Check your state’s laws for more information.

Exchange Information— Obtain contact and insurance information from the other driver. This should include full name, contact details, insurance company and policy number, driver’s license and plate number, and vehicle model and description.

Document the Details— Take a moment to record your recollection of events. It’s a good idea to use your phone’s camera to take pictures of the damage, the accident scene and injuries in case a future dispute should arise.

Report It to Your Insurance Agent or Company— Contact your insurance agent or company and have the proper damage assessment done right away.

Categories
Uncategorized

Renters Insurance Simplified

Renters Insurance Simplified

Are you one of the 37 percent of renters who have a renters insurance policy? Whether your rental agreement requires it or you make the choice to protect the contents of your rental property, this type of policy can provide peace of mind. It can come in handy if you face unexpected situations, like theft or fire, or if an individual is injured while in your home.

But do you fully understand what the policy covers and what to expect should you file a claim? Here’s a breakdown of a few important points.

Replacement Cost Value vs. Actual Cash Value
There are two choices when it comes to how renters insurance values belongings. Replacement cost value determines the amount paid out for a claim based on the present-day cost of buying the same item. Other policies may use actual cash value (ACV), which takes into account depreciation due to normal wear and tear. This type of coverage will pay out less than current market value.

Deductibles
A deductible is an out-of-pocket amount a policyholder is responsible for when a claim is filed. In general, the higher the deductible, the lower the monthly insurance premium. Once the deductible is met, the insurance company handles the remaining cost.

Discounts
Most insurance companies offer discounts if you bundle renters insurance with other policies, such as auto insurance. Safety equipment, like fire alarms and security systems, may result in a reduced rate. Age, good credit and a claim-free history are other factors that insurance companies may consider for discounts.

Umbrella Policies
If after a careful inventory of your personal possessions and net worth you determine you need a higher degree of liability coverage, you may decide to purchase an additional umbrella liability policy. This option provides coverage on top of other policies, kicking in once those have been maxed out.